Mobile Notary & Loan Signing Blueprint
Blueprint Course
Mobile Notary & Loan Signing Blueprint
Appointments, stamps, and signing-table professionalism.
This course is for someone who wants to build a mobile notary and loan signing business — driving to homes, offices, hospitals, and title companies to witness signatures for a fee. Understand the two income streams before you spend a dollar, because they are wildly different: general notary work (acknowledgments, jurats, oaths) pays $5 to $15 per notarial act because most states CAP those fees by law — you cannot charge more for the act itself no matter how good you are — plus a separately charged travel fee where your state allows one. Loan signings are the real revenue: walking a borrower through a 100-to-250-page mortgage, refinance, or HELOC package pays $75 to $200 per appointment. The catch is that your commission is a state appointment (application, bond, exam, and training vary by state), and several attorney-closing states restrict non-attorney real estate closings — so both your setup steps and your loan-signing ceiling depend heavily on where you live, and this course tells you to verify both before committing. Every money example uses the same explicitly stated base case: 8 to 15 signings a month part-time growing toward 20 to 40 a month full-time in good markets, roughly $5 to $15 in variable costs per signing (printing, toner, fuel), roughly $100 to $200 a month in fixed costs (E&O insurance, background screening, listing-site profiles), and $300 to $1,000 in startup costs (commission, bond, stamp, journal, dual-tray laser printer). Under that base case, part-time volume works out to very roughly $300 to $2,700 a month before tax, and full-time volume in a good market to very roughly $1,000 to $7,700 a month before tax — planning ranges under stated assumptions, not promises. Loan-signing volume rises and falls with the mortgage and refinance market, and no income is guaranteed.
What you get
Built for operators who want a clear path — not a pile of generic tips.
The base case
One worked example, not a target
Planning estimates, before tax and before anything you pay yourself — no income is guaranteed. Your own prices, volume and costs will differ; the course walks you through replacing every number here with yours.
Who this fits
- You are detail-obsessed: a loan package fails over one missed initial or a wrong date, and title companies remember who makes errors
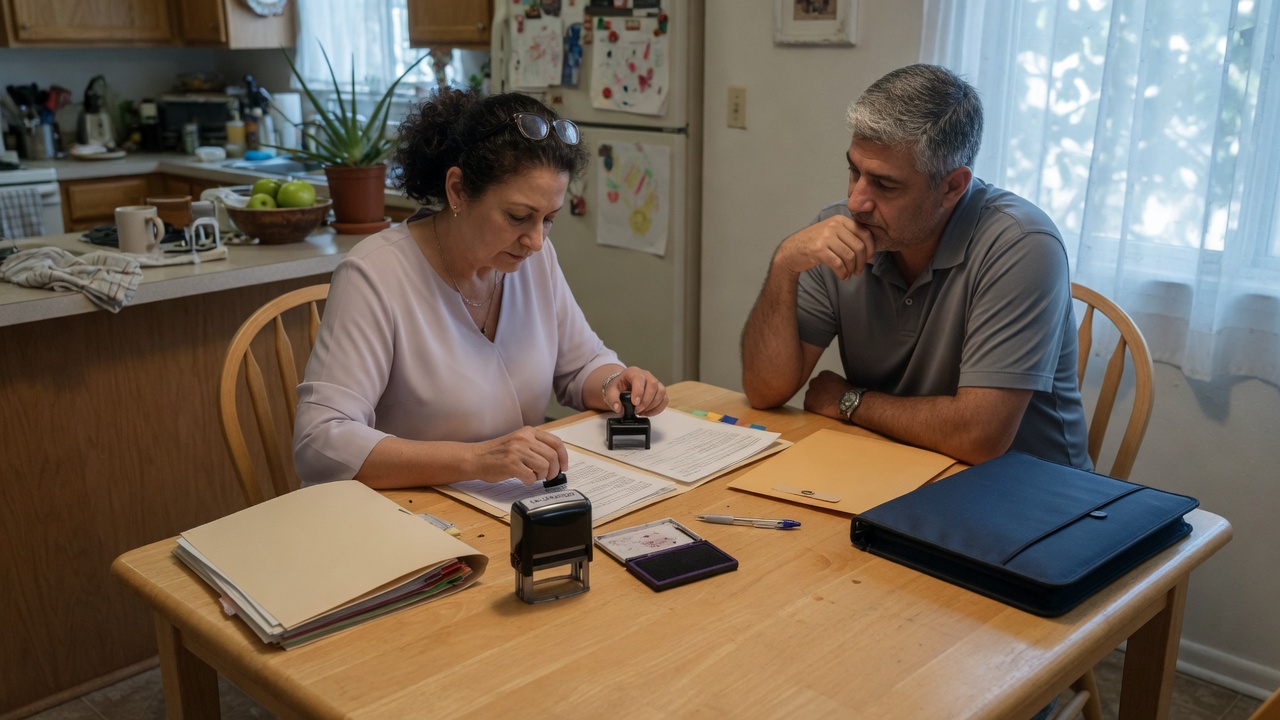
- You are comfortable driving to strangers' kitchen tables at 7 p.m. and staying calm, neutral, and professional for an hour
- You can follow rules exactly — notary law is procedural, fees are state-capped, and improvising is how commissions get revoked
- You want a lean, credential-based launch: $300 to $1,000 in, no inventory, no storefront
- You like the idea of two lanes — quick capped-fee general notary work for steady local demand, and higher-paying loan signings as the growth engine
Honest risks
- Your entire ability to operate is a state appointment. Application steps, exams, training, bond amounts, journal rules, and fee caps all vary by state, and violating them — even by overcharging a capped fee — can mean losing the commission the whole business sits on. Everything in this course is location-dependent: verify with your state's Secretary of State (or equivalent notary authority) before acting.
- General notary fees are capped by state law at roughly $5 to $15 per act in most states. You cannot out-market a fee cap; the business only scales through travel fees where allowed, volume, and loan signings.
- Loan-signing volume tracks the mortgage and refinance market, which tracks interest rates. When rates rise, refi signings can drop sharply within months — agents who built on refi volume alone have watched income fall by half or more, and no income is guaranteed.
- Several attorney-closing states restrict real estate closings to attorneys, which limits or eliminates the loan-signing side of this business there. If you live in one, your ceiling is materially lower — check before you build a plan around signing income.
- You are a neutral public official, not an advisor. Explaining what a loan document means, helping someone choose a notarial act, or advertising in ways that imply legal authority is unauthorized practice of law — fines, lawsuits, and commission revocation are real outcomes.
- One serious signing error — a missed signature, a bad certificate, a blown drop-off deadline — can end a title-company relationship that took months to earn. This is a reliability business with a memory.
Who should skip this one
- You are counting on loan signings as dependable income. Signing volume tracks the mortgage and refinance market — when interest rates rise, refi packages can dry up fast, established agents absorb the remaining volume, and newcomers feel it first. If you need steady, predictable income in the next 90 days, this is the wrong plan, and no income is guaranteed.
- You live in an attorney-closing state and expected loan signings to be the business. Several states restrict non-attorney real estate closings, which limits or removes the $75–$200 appointments — leaving mostly $5–$15 state-capped general notary work plus travel fees. Verify your state's rules BEFORE buying a printer.
- You are not a detail person. This work is initials on page 43, a date written three different ways, the right certificate stapled to the right document, and a courier deadline — done perfectly, every time, often at night. If precision under mild time pressure drains you, the error rate will end the business.
- You may not pass a background screening, or your state's commission eligibility rules. Title and signing companies commonly require annual background checks, and states set their own eligibility standards for commissions — check both honestly before spending anything.
- You want to advise people. A notary is a neutral witness — you may not explain what documents mean, recommend a notarial act, or help someone decide whether to sign. If you cannot repeat 'that's a question for your loan officer or an attorney' all day, this role will chafe or get you in legal trouble.
Curriculum
10 modules · 34 lessons · 1 hr 35 min of reading
01Is the Mobile Notary Business Right for You?3 lessons · 9 min
The two income streams, the state-appointment reality underneath them, and an honest fit check before you spend a dollar.
- The Business: Two Very Different Income Streams3 min
- You Are Applying for a State Appointment3 min
- The Job Behind the Job: An Honest Fit Check3 min
02Getting Commissioned and What It Costs3 lessons · 9 min
The state commission process, the full $300–$1,000 startup budget, and the signing-agent credential layer title companies expect.
- Step One: Your State's Commission Process3 min
- The Real Startup Budget: $300 to $1,0003 min
- The Signing-Agent Layer: What Title Companies Expect3 min
03Equipment and Supplies3 lessons · 7 min
The stamp-and-journal core, the dual-tray printer that makes loan signings possible, and the mobile kit that makes you look like a professional at the door.
- The Core: Stamp, Journal, Certificates2 min
- The Printer Is the Business3 min
- The Mobile Office Kit2 min
04Services and Pricingfree sample4 lessons · 12 min
State fee caps and travel fees, what loan signings actually pay, general-notary niches worth building, and a pricing floor computed from your real costs.
- The Honest Foundation: Fees Are Capped by Your State(free sample below)3 min
- What Loan Signings Really Pay3 min
- General Notary Niches Worth Building3 min
- Price From Costs, Not Vibes3 min
05Legal, Insurance, and Taxes (Education Only)4 lessons · 12 min
The neutral-official rules that keep your commission, the attorney-closing-state restriction that shapes your market, the bond/E&O/journal protection stack, and the tax habits — all education, not legal advice.
- You Are a Neutral Official — the UPL Line3 min
- Attorney-Closing States: Check Before You Plan3 min
- Your Protection Stack: Bond, E&O, Journal3 min
- Taxes: The Set-Aside and the Mileage Log3 min
06Branding and Being Findable3 lessons · 7 min
A trustworthy professional identity, the listing profiles where signing work actually gets assigned, and a simple online presence that converts urgent searches.
- A Name That Signals Trust (and Stays Legal)2 min
- The Listing Profiles Where Work Gets Assigned3 min
- A One-Page Site That Converts Urgency2 min
07Marketing: Your First 10 Signings4 lessons · 11 min
Signing services for the first orders, direct escrow and title outreach for the better ones, local general-notary outreach for rate-proof demand, and a tracker that keeps the pipeline honest.
- Signing Services: Your First Orders3 min
- Direct Outreach to Escrow and Title3 min
- General-Notary Outreach: Demand Rates Can't Touch3 min
- Track Everything: The First-10 Sprint2 min
08Service Delivery: The Signing Itself4 lessons · 11 min
The confirm-and-prep routine, flawless table procedure, the scanback-and-drop endgame, and how professionals handle errors.
- Before the Table: Confirm and Prep3 min
- At the Table: Calm, Neutral, Exact3 min
- After the Table: Scanbacks, Drops, and Status2 min
- Errors: Prevention, Then Professional Recovery3 min
09Reviews, Referrals, and Getting Paid3 lessons · 8 min
Reviews that fill the databases in your favor, turning one-off orders into standing escrow relationships, and running the receivables so the money actually arrives.
- Reviews Are Ranking Fuel2 min
- From Orders to Relationships3 min
- Receivables: The Unsexy Skill That Keeps You Solvent3 min
10Growth: Density, RON, and Rate-Cycle Resilience3 lessons · 9 min
Route density that raises your real hourly, remote online notarization and specialty niches, and the diversification scorecard that survives the next rate cycle.
- Density: The Growth Lever Nobody Sees3 min
- RON and Specialty Niches3 min
- Surviving the Rate Cycle: The Diversification Scorecard3 min
Why people buy this
Built for first-time operators who want a clear path — not generic AI chat.
Honest fit check
Who should start — and who should skip — so you don't waste months on the wrong business.
Do-this-next lessons
Every lesson ends in an action: scripts, checklists, pricing math you can use this week.
One-time purchase
One payment of $59. No course subscription.
Mobile Notary & Loan Signing Blueprint is part of the OwnerLaunch founding library. Figures in the course are planning estimates before tax — no income is guaranteed.
Blueprint FAQ
Why $59 for this Blueprint?+
You get a full operator course (10 modules, 34 lessons), a free sample lesson before you buy, downloadable templates after purchase, and a path into a personalized Launch Kit if you want one. It's a one-time payment — not a subscription for the course itself.
What do I get before I pay?+
The full curriculum outline, honest fit/risk lists, money base-case assumptions, a short course preview video when available, and one complete free sample lesson — real course content, not a teaser paragraph.
Is this legal, tax, or financial advice?+
No. OwnerLaunch is educational only. Licensing, insurance, tax, and filing requirements are location-dependent — verify with official sources and licensed professionals.
Can I upgrade to a Launch Kit later?+
Yes. Blueprint owners typically pay only the difference for a personalized Launch Kit (names, brand, pricing, copy, documents, 30-day plan). The course and kit are separate purchases.
Included templates & tools
- 30-Day Launch Checklist — The whole course sequenced into four weeks — commission and credentials first, then equipment and pricing, then profiles and outreach, then first signings delivered flawlessly.
- Outreach & Follow-Up Scripts — Word-for-word scripts: escrow/title introduction, care-facility and law-office intros, signing confirmation call, review ask, monthly value touch, and the polite payment chase.
- Signing Day Prep & Confirmation Sheet — A fill-in sheet completed for every signing: order details, confirmation-call record, print verification, drop logistics, and the after-table closing loop.
- Pricing & Fee Floor Calculator — Hand-computed worksheet: variable cost per signing, fixed-cost share, loan-signing floor, lawful travel-fee pricing, and the before-tax monthly picture under the base case.
- Signing-Table Scope Self-Check — Ten scenario questions on the notary / loan-officer / attorney boundary — take it before your first signing and again whenever a table moment felt gray.
- Signing Quality & Closing-Loop Checklist — The before / at-the-table / after habits that produce a near-zero error rate and the reliability reputation escrow officers hire for — laminate-and-keep format.
Free sample lesson
Real course content — not a teaser paragraph. The rest unlocks after purchase.
From module: Services and Pricing
The Honest Foundation: Fees Are Capped by Your State
~3 min read
Here is the fact this whole business is priced around, and the one most beginner guides bury: for general notary work, YOU do not set the price of the notarial act — your state does. Most states cap the fee per act by statute, commonly somewhere between $5 and $15 for an acknowledgment, and charging above the cap is a violation that can cost you your commission. So the mobile notary business model is really a travel business: the act fee is capped, but many states let you charge a separate, disclosed travel or convenience fee for coming to the signer. Some states cap or regulate travel fees too; some require you to quote them in advance; a few are silent. Your pricing page is therefore built from three questions: what is my state's per-act cap, what are my state's travel-fee rules, and what does a trip actually cost me?
- Per-act fee: capped by state law in most states ($5–$15 is the common range). Never exceed it, never obscure it — quote 'the state-set notary fee plus my travel fee' so signers see you charging lawfully.
- Travel fee (where allowed): this is where mobile notaries actually earn — commonly $25–$50+ per trip depending on distance and time of day, set by YOU from real costs unless your state caps it.
- Loan signings are different: the $75–$200 appointment fee is a service package (printing, travel, procedure, courier) paid by the hiring company — not a per-act notary fee — which is why it escapes the cap structure.
- Location-dependent: caps, travel-fee rules, and disclosure requirements vary by state and change by legislation — verify your state's current fee schedule with the Secretary of State before quoting anyone.
Action · task
Write your two-line fee quote
Using your state's actual cap (from Module 1) and travel-fee rules, write the exact two-line quote you will give general-notary callers: per-act fee at or under the cap, plus your travel fee (if allowed) with when it applies. Say it out loud twice.
Ready to make it yours?
A Launch Kit turns this Blueprint into your business: personalized name, brand, pricing, website copy, documents, and Action Plan.
Basic
$119 current
Pro
$199 current
Apply your Blueprint credit to Basic for +$60 or Pro for +$140.
More Blueprints
Related course · Beauty & Personal Care
Mobile Massage Blueprint
Licensed massage without the spa's overhead.
Related course · Home Services
Home Organizing Blueprint
Launch a home organizing business — from your first portfolio closet to a calendar of paid sessions.
Recommended next · Local Professional
Dog Walking & Pet Sitting Blueprint
Midday routes and overnight stays on repeat.
Recommended next · Local Professional
Real Estate Photography Blueprint
The agent reshoots every month — win the turnaround, keep the client for years.
Recommended next · Local Professional
Senior Companion (Non-Medical) Blueprint
Companionship and errands for aging neighbors.
All figures in this course are before-tax planning estimates under an explicitly stated base case — a mobile notary and loan signing agent charging state-capped general notary fees of $5–$15 per notarial act (caps are set by each state's law and must never be exceeded) plus separately charged travel fees where the state allows them, earning $75–$200 per loan signing appointment, completing 8–15 signings per month part-time building toward 20–40 per month full-time in good markets, with roughly $5–$15 in variable costs per signing (printing, toner, fuel), roughly $100–$200 per month in fixed costs (E&O insurance, background screening, listing-site profiles), and $300–$1,000 in startup costs (commission application, surety bond, stamp, journal, dual-tray laser printer). These figures are not inherited from a Discover profile; they are stated assumptions to verify against your state's fee schedule, current signing-service rate sheets, and real quotes. A notary commission is a state appointment whose application, training, exam, bond, journal, fee, and advertising rules vary by state, and several attorney-closing states restrict non-attorney real estate closings — verify everything with your Secretary of State, state notary handbook, and state bar before acting. Loan-signing volume tracks the mortgage and refinance market, which tracks interest rates. Nothing here is legal, tax, or insurance advice; this course never files anything for anyone (an EIN, if you want one, is free directly from the IRS), and no income is guaranteed.
Educational guidance only — not legal, tax, or financial advice.Details
OwnerLaunch provides educational business guidance, AI-generated drafts, and checklists. It is not a law firm, tax advisor, CPA, registered agent, or government agency. Information may not be complete or current for your specific location. Always verify requirements with official federal, state, city, and county sources and consult qualified professionals when needed.